

At The Platinum Group, we are a People-Powered, Client-Focused, and Results-Driven organization. Our mission is to provide financial services for small to mid-size businesses through a seamless integration of insurance and risk management. We are committed to guiding you every step of the way, offering personalized solutions that match your business’s unique needs. With that in mind, we present this midyear market outlook to help you navigate the evolving landscape of general liability insurance in 2025.
Let us guide you toward smarter, safer, and more resilient coverage strategies. Contact us today at 909.466.7876 for more information on General Liability insurance and Commercial Insurance! Also, discover Cyber Insurance 2025 Midyear Market Outlook and how your business can stay cyber safe in the digital age.
A Calmer General Liability Insurance Market Emerges—But with Caveats
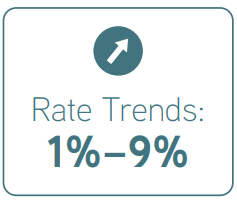
Over the past few years, general liability insurance has slowly shifted from turbulent conditions to a more stable environment. This improvement stems from better underwriting performance and a softening of premium increases. For instance, most policyholders since early 2023 have seen modest, single-digit rate hikes, supported by healthy market capacity.
In the last quarter of 2024, average premium increases hit 5.3%, up slightly from 4.8% the quarter before. So far in 2025, this trend has continued, with rate hikes averaging just above 4%.
Who’s Seeing Stability—and Who’s Not
While many insureds benefit from this moderation—especially those with fewer exposures and strong risk management practices—others still face challenges. Businesses in higher-risk sectors like construction, hospitality, retail, and real estate, or those with a history of frequent losses, may experience larger premium hikes and tighter coverage restrictions.
Legal Trends Continue to Drive Up Costs
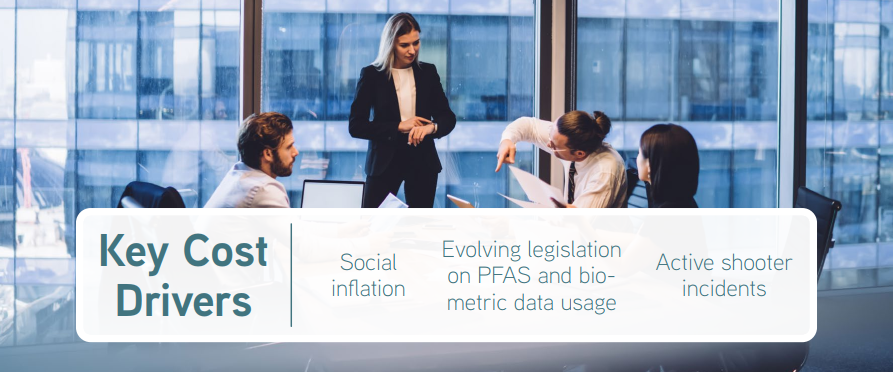
Despite this relative stability, troubling cost drivers remain. For one, the U.S. remains a highly litigious environment, and lawsuits following liability events—whether real or alleged—are on the rise. These legal battles are expensive, largely due to social inflation: the tendency for jury awards and settlements to climb as public attitudes toward litigation evolve.
As a result, plaintiffs’ attorneys are advertising more aggressively, third-party litigation funding (TPLF) is increasing, and nuclear verdicts (awards exceeding $10 million) are more frequent. Consequently, businesses may face complex claims and high out-of-pocket expenses, even with coverage in place.
Emerging Risks Add Pressure
In addition to social inflation, new exclusions are surfacing. Many insurers now limit or remove coverage for liability tied to PFAS—chemicals found in various consumer goods that have come under scrutiny for health risks. Companies that use PFAS may now be more exposed to costly claims alleging illness due to chemical exposure.
Likewise, the growing use of biometric data (like fingerprint scans or facial recognition) has opened another area of liability. Since there’s no federal standard and many states are implementing their laws, businesses struggle to keep up with compliance. Worse, general liability policies often don’t address biometric data claims, leaving coverage uncertain. Some carriers are already updating policy language to exclude this risk entirely.
Active Shooter Events Raise New Concerns
Unfortunately, another rising threat is active shooter incidents. These tragic events can cause severe physical, emotional, and financial damage. When they occur on a business’s premises, the company could be held responsible for not protecting employees or visitors.
Adding to the problem, many general liability policies exclude claims involving intentional violent acts or emotional trauma, leaving insureds with minimal protection. To bridge the gap, some have started purchasing specific endorsements or standalone coverage.
What to Expect Through the End of 2025 for General Liability Insurance
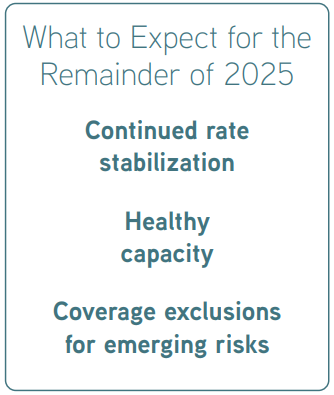
Looking ahead, policyholders can expect continued rate stability and sufficient capacity in the general liability insurance market. However, rates and terms will vary depending on a business’s industry, risk profile, and location.
Those operating in litigation-prone sectors or jurisdictions should be prepared for tougher underwriting and more frequent coverage limitations. No matter your business’s size or sector, it’s essential to:
- Review your policy language carefully for changes to exclusions
- Pay close attention to PFAS, biometric data, and active shooter-related clauses
- Consider additional coverage options if needed to fill potential gaps
At The Platinum Group, we understand how overwhelming insurance decisions can be. That’s why we remain committed to helping our clients adapt to shifting market conditions, ensuring their policies evolve with their risks.
