

At The Platinum Group (TPG), we are a People-Powered, Client-Focused, and Results-Driven organization. Our mission is to support small to mid-size businesses through tailored financial services that combine insurance and risk management strategies. As we guide clients through evolving market conditions, we remain committed to providing clear insights and strategic solutions that align with their unique business needs. We want to keep our clients knowledgeable of the trends and updates that affect the market for Commercial Insurance. Let’s take a look at the commercial auto insurance midyear market outlook and what this could mean for your business.
Contact us to learn more about our Commercial Auto Insurance Solutions for your business! Call us at 909.466.7876 today! Also, check out this eye-opening article on our blogs/resources page: What is Fleet Fraud — And How to Prevent It
Overview of Current Commercial Auto Insurance Market Conditions
Over the past decade, commercial auto insurance has faced consistent pressure. Rising claim frequency, increasingly severe losses, and litigation challenges have significantly reduced underwriting profitability. As a result, the market has hardened, making it more difficult—and costly—for businesses to secure comprehensive coverage.
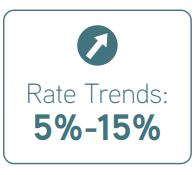
Consequently, the vast majority of policyholders have encountered significant rate hikes for several years.
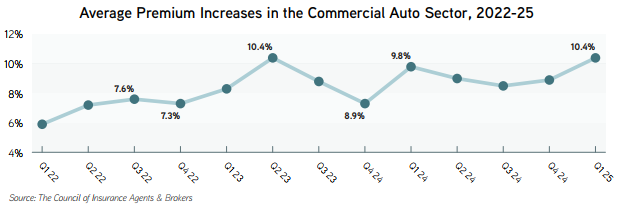
Recent data reinforces this trend. In Q4 of 2024, premium increases averaged 8.9%, slightly up from 8.5% the previous quarter. So far, in the first half of 2025, rate hikes have continued to climb, averaging just over 10%. Businesses with higher exposures—such as large fleets or poor claims histories—have experienced the sharpest premium spikes and reduced market capacity.
Technology’s Double-Edged Impact
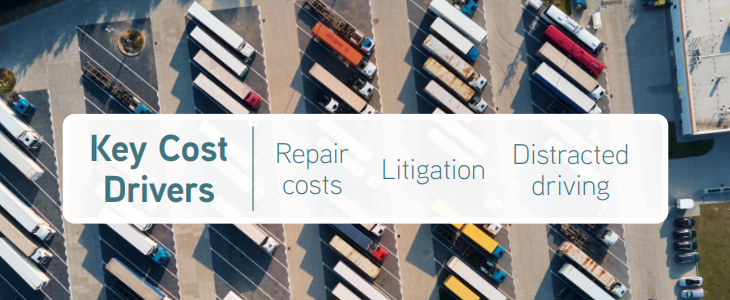
While technological advancements have contributed to safer and more efficient vehicles, they have also made repairs far more expensive. Many modern commercial fleets are equipped with advanced sensors and electronics, which, when damaged, significantly drive up repair costs. To complicate matters further, recent U.S. tariffs on imported parts have created supply chain issues, potentially increasing repair costs even more.
Contact us to learn more about our Commercial Auto Insurance Solutions for your business! Call us at 909.466.7876 today! Also, check out this eye-opening article on our blogs/resources page: What is Fleet Fraud — And How to Prevent It
Consequently, insurers are reassessing their pricing models to account for these additional risks. Businesses should expect continued premium adjustments as carriers evaluate loss trends and operational expenses.
The Ongoing Burden of Litigation
In addition to escalating repair costs, litigation continues to play a major role in rising insurance expenses. Notably, social inflation—influenced by public sentiment and legal norms—has led to more aggressive third-party litigation funding (TPLF). This trend enables frequent and high-dollar lawsuits, especially after severe or fatal accidents.
As a result, “nuclear verdicts,” or jury awards exceeding $10 million, have become increasingly common. The American Transportation Research Institute reports that these verdicts have doubled in the trucking industry over the past decade. This legal environment has pushed many insurers to tighten coverage, reduce their risk appetite, or leave the market entirely, leaving policyholders with fewer options.
The Impact of Unsafe Driving
Furthermore, unsafe driving behaviors among commercial drivers continue to drive up risk. Distracted driving—such as texting, adjusting controls, or eating while driving—has become alarmingly common. According to the National Highway Traffic Safety Administration, such behavior was responsible for nearly 3,300 deaths and 325,000 injuries in 2023 alone.
These habits not only increase claim costs but may also trigger regulatory penalties, especially in states where certain distractions (like texting) are illegal. Therefore, policyholders with poor driving records often face steeper premiums and potential legal exposure.
Looking Ahead: Planning for the Second Half of 2025
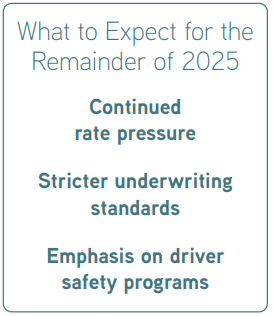
As we look to the remainder of 2025, most indicators suggest that the commercial auto insurance market will remain a hard market. Insurers are expected to continue implementing rate increases, particularly for businesses with inadequate safety protocols or poor loss history. Those with proactive driver safety programs and risk mitigation measures will be best equipped to navigate these challenges. Moreover, exploring coverage options in the excess and surplus lines market or considering alternative risk transfer strategies may help businesses avoid coverage gaps and better control costs.
At TPG, we understand that every business faces unique risks. That’s why our mission is rooted in delivering personalized insurance and risk management solutions that empower our clients to thrive, even in challenging market conditions.
